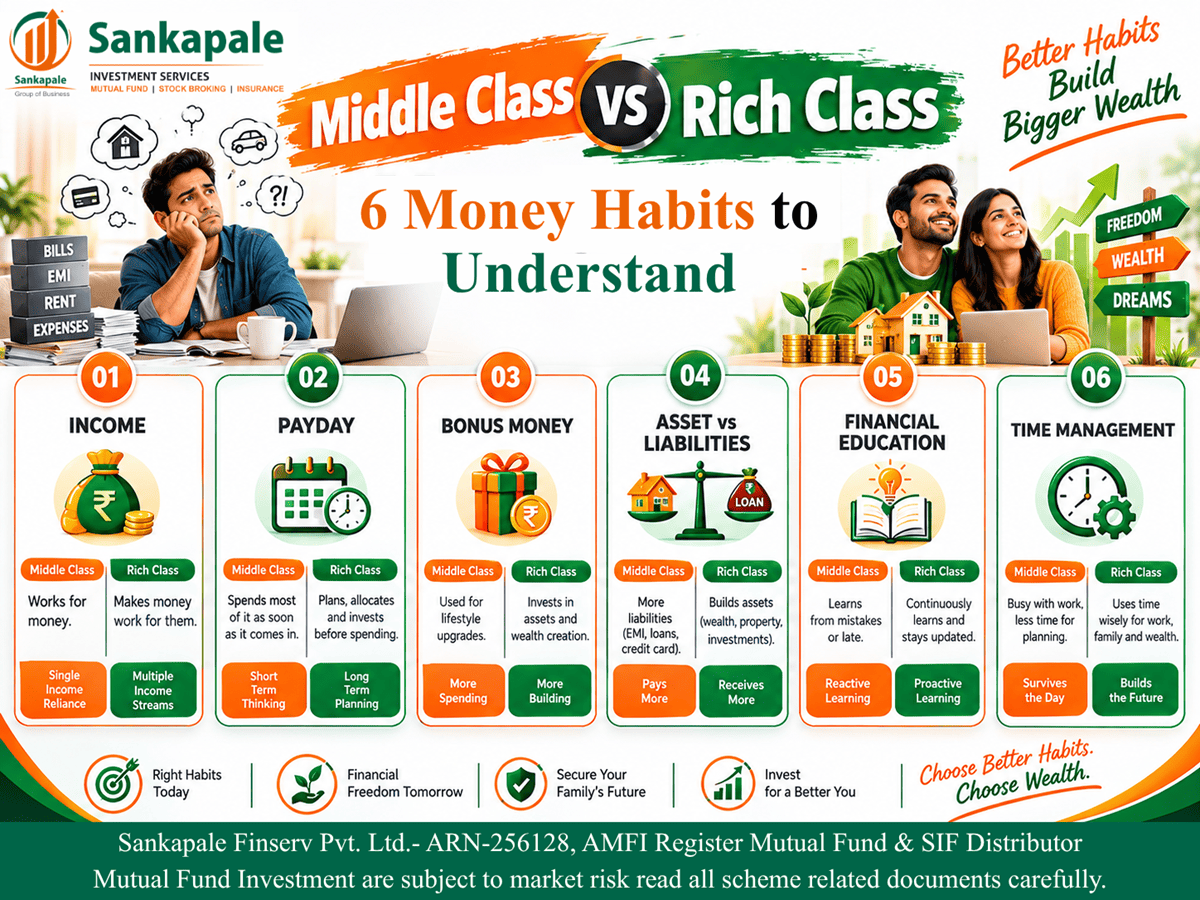
Middle Class vs Rich Class : 6 Money Habits to Understand
Middle Class vs Rich Class : 6 Money Habits to Understand
Money management is not only about how much you earn. It also involves how you plan your income, manage expenses, save, invest, protect your finances and use your time.
Different people may have different financial circumstances and priorities. Instead of viewing financial habits as “middle class vs rich class,” it can be more useful to understand the habits that may support disciplined financial planning and long-term wealth creation.
Here are six important money habits to consider.
1. Income : Earning More and Managing Better
Income is an important part of financial planning.
As income changes over time, expenses and lifestyle choices may also change. A financial plan can help you decide how much of your income should be allocated toward current expenses, savings, investments and financial goals.
Consider :
- Increasing your earning potential.
- Tracking monthly income and expenses.
- Maintaining an appropriate savings habit.
- Allocating money toward defined financial goals.
- Reviewing your financial plan as income changes.
Key takeaway : Higher income can provide greater financial capacity, but disciplined money management remains important.
2. Payday : Plan Before You Spend
When income is received, having a predetermined allocation can help prevent unplanned spending.
Instead of deciding what to do with the money only after expenses occur, consider creating a monthly plan.
A simple framework :
Income → Essential Expenses → Savings → Investments → Discretionary Spending
You may consider :
- Setting a monthly budget.
- Automating regular savings or investments.
- Prioritising essential expenses.
- Keeping adequate emergency reserves.
- Reviewing discretionary spending.
The objective is not to eliminate spending. It is to allocate money according to your priorities and financial goals.
3. Bonus Money : Enjoy Some, Plan Some
A bonus or other additional income can be used in different ways depending on your financial circumstances.
Before spending the entire amount, consider whether part of it could support an existing financial priority.
Additional income may be allocated toward:
- Emergency savings.
- Planned expenses.
- Repayment of outstanding debt.
- Long-term investments.
- Other financial goals.
- Reasonable discretionary spending.
There is no single allocation that is suitable for everyone.
Key takeaway : Treat additional income as an opportunity to review your financial priorities rather than automatically increasing recurring expenses.
4. Assets vs Liabilities : Understand What You Own and Owe
Understanding assets and liabilities is an important part of financial planning.
Assets may include investments, property and other holdings that form part of your financial position.
Liabilities may include loans, EMIs and other financial obligations.
Before taking on a significant financial commitment, consider:
- Total outstanding debt.
- Interest costs.
- Monthly repayment obligations.
- Existing assets and investments.
- Emergency liquidity.
- Long-term financial goals.
The objective is to understand how each financial decision affects your overall financial position and cash flow.
5. Financial Education : Keep Learning
Financial products and investment options involve different characteristics and risks.
Developing financial knowledge can help you understand concepts such as:
- Budgeting.
- Inflation.
- Emergency funds.
- Insurance.
- Mutual funds.
- SIPs.
- Asset allocation.
- Diversification.
- Risk and return.
- Retirement planning.
- Tax considerations.
Investment decisions should be based on factors such as financial goals, investment horizon, risk tolerance, liquidity requirements and individual circumstances.
Key takeaway : Financial education can help investors make more informed decisions, but it does not eliminate investment risk.
6. Time Management : Make Time for Financial Reviews
Financial planning is not a one-time activity.
Income, expenses, family responsibilities, financial goals and investments can change over time. Regular reviews can therefore be useful.
Periodically review :
- Your savings.
- Your investments.
- Your financial goals.
- Your insurance coverage.
- Your outstanding liabilities.
- Your emergency fund.
- Your retirement planning.
A review does not necessarily mean changing investments frequently. It means checking whether your financial plan continues to align with your circumstances and objectives.
Build Better Financial Habits
There is no universal formula for becoming wealthy.
Different people have different incomes, responsibilities, financial goals, risk tolerance and investment horizons.
Instead of comparing yourself with a particular income group, focus on developing practical financial habits:
Earn → Plan → Save → Invest → Protect → Review
Consistency, informed decision-making and appropriate financial planning can support your long-term financial objectives.
Final Thoughts
Your financial journey is personal.
The important question is not:
“Do I have a rich-class money habit?”
Instead, ask :
“Are my current money habits aligned with my financial goals?”
Start with your income.
Plan your expenses.
Save regularly.
Invest according to your objectives and risk profile.
Protect your finances.
Review your plan periodically.
Plan. Invest. Review. Grow.